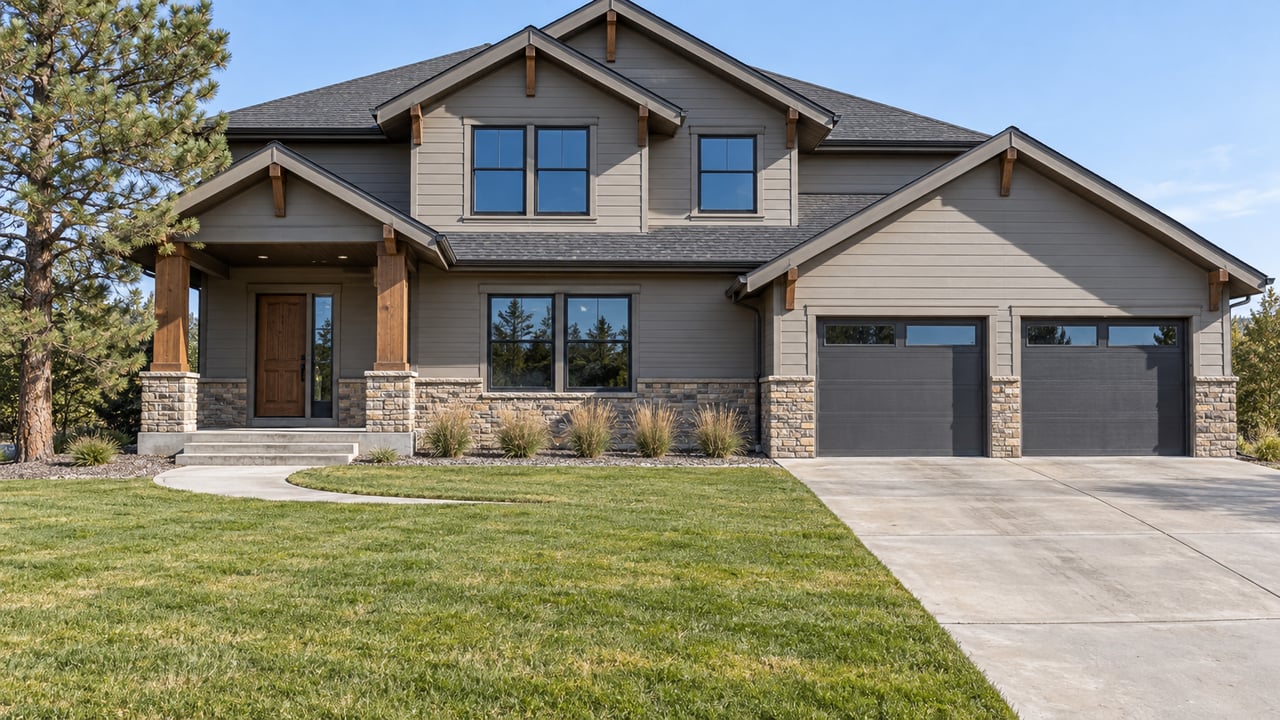
A new three-bedroom, 2,199-square-foot Van Buren plan on a cul-de-sac at 10933 Pura Vida Way in Challenger Homes' Ventana South carries an advertised price of $455,900, already $35,000 below its original $490,900. In the builder's own financing example, the VA loan on that same home comes to $519,867.64. That is $63,967.64 more than the advertised price.
The gap comes from how many new-construction incentives around Fountain work this fall. The incentive that lowers your monthly payment can raise the contract price, and the loan sits on top of that higher price. For new homes here, the sticker, the contract price and the loan amount can be three different numbers, and the appraisal decides which of them holds.
One Home, Three Numbers
Challenger's payment example for Pura Vida Way breaks the stack down line by line.
| Layer | Amount | What it is |
|---|---|---|
| Advertised price | $455,900.00 | After a $35,000 reduction |
| 3-2-1 buydown cost | $45,025.74 | 8.661% of the loan |
| Modeled seller credit for closing costs | $8,000.00 | Assumed closing costs |
| Modeled adjusted contract price | $508,925.74 | Advertised price plus buydown and credit |
| VA funding fee, financed | $10,941.90 | 2.15%, added to the loan |
| Loan amount | $519,867.64 | 30 years, 0% down |
The math lines up exactly. The $53,025.74 gap between the advertised price and the contract price equals the buydown cost plus the $8,000 closing-cost credit. Add the financed funding fee and you get the loan amount. The listing says financing costs "are modeled through a higher contract price and seller credits, subject to lender approval and appraisal support."
The listing also describes the $45,000 in available incentives as flexible, meaning a buyer can put them toward a lower purchase price, eligible financing costs or a mix of the two. So the same incentive money could produce a smaller loan with a higher payment, or a larger loan with a lower starting payment. The way the incentive is split decides which one the buyer gets.
The Payment Climbs on a Schedule
A temporary buydown lowers the rate for a few years. The note rate never changes. Fannie Mae's rules say a temporary buydown can't change the terms of the mortgage note, the borrower has to qualify at the note rate, and the plan can run no longer than three years with the rate rising no more than one point a year. Read the full temporary buydown provisions in Fannie Mae's Selling Guide.
On the Pura Vida Way VA example, the estimated monthly payment rises like this:
- Year 1 at 3.5%: $2,918.29
- Year 2 at 4.5%: $3,217.95
- Year 3 at 5.5%: $3,535.61
- Year 4 onward at the 6.5% note rate: $3,869.77
From year one to year four, the payment goes up $951.48 a month. The example holds taxes, insurance and the $47 monthly HOA/metro estimate constant, and the builder notes that those amounts can change. The year-four payment is the one the loan is underwritten on, and it is set on a contract price of $508,925.74.
Where the VA's Four Percent Rule Fits
A lot of the buyers looking near Fort Carson use VA financing, which puts one rule at the center of this. The VA Lender's Handbook, Chapter 8, Topic 5 defines a seller concession as anything of value the builder or seller adds that the buyer doesn't pay extra for and that the seller isn't customarily expected to provide. Its list includes paying the buyer's VA funding fee and "provision of escrowed funds to provide temporary interest rate buydowns."
Topic 5(d) sets the limit on those concessions:
"Any seller concession or combination of concessions which exceeds four percent of the established reasonable value of the property is considered excessive, and unacceptable for VA-guaranteed loans."
The handbook says normal discount points and payment of the buyer's closing costs don't count toward that 4%. VA's consumer page on closing costs makes the same distinction. Closing-cost credits from a seller or builder have no limit, while concessions are capped at 4% of reasonable value.
Here is the arithmetic for a home in this price range. Four percent of $455,900 is $18,236. Four percent of $508,925.74 is about $20,357. The 3-2-1 buydown in Challenger's example costs $45,025.74. The handbook also says why the cap exists. In some places builders use concessions as a competitive tool, and in extreme cases those concessions can hide whether a veteran can actually afford the loan. The "reasonable value" in that rule comes from the appraisal, and so does the "appraisal support" condition in the builder's fine print.
Three Builders, Three Structures
Builders near Fountain aren't all offering the same thing this fall, and the differences decide which numbers move. Here is what was advertised as of early November 2026.
| Builder and community | Address | Starting price | Incentive structure | Deadline and conditions |
|---|---|---|---|---|
| Challenger Homes, Ventana South | 11190 Feliz Way, Fountain 80817 | $373,900 | Price reductions plus VA 3-2-1 buydown, with costs modeled through contract price | Subject to lender approval and appraisal |
| View Homes, Aspen Ranch | 9715 Cronin Street, Fountain 80817 | $439,995 | "Special incentives" on select homes, amount not listed | Not listed |
| View Homes, Ridge at Lorson Ranch | Colorado Springs 80925 | $414,995 | FHA and VA 2-1 buydown: 3.75%, 4.75%, then 5.75% | Contract and close by December 23, 2026 |
| D.R. Horton, Ridge at Lorson Ranch | Colorado Springs 80925 | $396,990 | Fixed 5.50% FHA, 6.362% APR, or 5.99% conventional, 6.400% APR | Must use DHI Mortgage; contract on or after 9/29/26, close by 1/29/27 |
The D.R. Horton offer is a fixed rate, so the payment doesn't step up. The terms come with conditions, though. The rate is available only through its affiliate DHI Mortgage, it isn't available for every credit profile, it may require the buyer to pay points, and it may not combine with other offers. Its example uses a $484,995 sales price and a $476,211 FHA loan. On top of that, D.R. Horton's Main Street Stars program offers military veterans and current military personnel up to $2,000 toward closing costs or upgrades, usable with any lender, through December 31, 2026. Its terms say incentives combined with other seller offers "may not exceed loan program limitations."
The limits differ by loan type. Fannie Mae's interested-party contribution rules count builder-funded temporary and permanent buydowns toward caps of 3% above 90% loan-to-value, 6% between 75.01% and 90%, and 9% at 75% or below. Anything over the cap is treated as a sales concession and subtracted from the price. For FHA, HUD Handbook 4000.1 caps interested-party contributions at 6% of the sales price, and that 6% includes temporary and permanent rate buydowns.
Why Resale Sellers Feel It Too
The appraisal is where incentives start to affect older homes nearby. Fannie Mae requires the appraiser to receive the sales concessions in a deal, including price discounts and rate buydowns. HUD lists special financing and upgraded features in new construction as sales concessions. Both tell appraisers to adjust comparable sales based on how the market reacts to a concession, not to subtract its dollar cost. So a recorded new-home sale at a price that includes financing costs doesn't automatically become a clean comparable for the resale house down the road.
The broader market gives builders room to compete this way. In its October 4, 2026 report on the regional market, The Gazette said new development in El Paso County has mostly gone up on the east side and farther south toward Fountain. It quoted a local agent who said areas near new construction tend to favor buyers, and that builder closing-cost credits and lower in-house rates make it harder to sell older existing homes. The same report put the region's August 2026 single-family median sale price at $470,000, down from a 2026 high of $499,952 in May. Freddie Mac's 30-year fixed average was 7.03% as of September 24. When resale homes are financed near 7%, a builder's 3.5% first-year rate is a strong selling point, even though the loan underneath is written at the note rate.
The most recent figures from the Pikes Peak Association of Realtors, for September 2026, show 1,101 closed sales across the region, a $450,000 median sale price and an average of 59 days on market, counting all property types. PPAR's detailed August 2026 report puts El Paso County at 3,218 active listings and a $475,000 median sold price. Ventana South's $373,900 starting price is well below either median. That comparison only holds at the sticker, though, before any incentive gets built into the contract.
Questions We Hear About Fountain New-Build Incentives
Is the advertised price the price on my contract? Not always. In Challenger's Pura Vida Way example, the contract price is modeled at $508,925.74 against a $455,900 advertised price, because the buydown and closing-cost credit are built into the price.
Does a fixed builder rate avoid the step-up? D.R. Horton's offer is a fixed rate, so the payment stays level. To get it, you have to finance with DHI Mortgage, and you may have to pay points.
Are all of these homes inside Fountain? Ventana South and Aspen Ranch have Fountain 80817 addresses. Both Ridge at Lorson Ranch communities list Colorado Springs 80925 addresses.
Do these offers last? Each one has a date on it. View Homes' buydown requires closing by December 23, 2026. D.R. Horton's rate requires closing by January 29, 2027. Main Street Stars runs through December 31, 2026.
This post is general information, not legal, tax or financial advice. Loan limits, concession rules and eligibility depend on your situation, so confirm the details with your lender and other qualified professionals before you sign.
Builder incentives near Fountain are worth taking seriously, and they're easier to judge once you've seen the contract price, loan amount and year-four payment side by side. CC Signature Group works on new-construction purchases every week. We'll go through each builder's offer with you, line by line, before you commit. If you already own a home nearby and want to know how it compares with these offers, start with Get Your Instant Home Valuation.